5 Sustainability Leadership Takeaways from ISS-Corporate's Oslo Roundtable
European corporate sustainability expectations are moving from disclosure to delivery, requiring companies to connect reporting, credible claims, transition planning, supply-chain accountability, and measurable execution with business resilience and long-term value.
Why Sustainability Leadership Is Being Re-Defined
Nordic companies have long been viewed as sustainability leaders. In today’s more demanding operating environment, that position cannot be assumed. At an ISS-Corporate roundtable in Oslo on 15 September, participants identified five tests of continued leadership: treating sustainability as a business resilience issue; responding to regulation through implementation, not compliance alone; making reporting decision-useful; integrating climate and social risks into supply-chain management; and closing the gap between ambition and execution. The conclusion was qualified: Nordic companies retain important strengths, but leadership will increasingly depend on disciplined delivery and measurable business outcomes.
Strengthen your climate strategy and reporting with ISS-Corporate’s sustainability solutions »
1. Sustainability Is a Business Performance Issue
Participants did not debate whether sustainability still matters. They focused on how physical climate impacts, resource constraints, human rights and supply-chain disruption affect operating continuity, costs and long-term value. Extreme weather is already visible in insurance claims, agricultural shortages and disrupted sourcing. The practical question for boards and management is therefore not simply what must be reported, but whether the business can perform under changing environmental and social conditions.
2. Sustainability Regulation is Shifting from Disclosure to Implementation
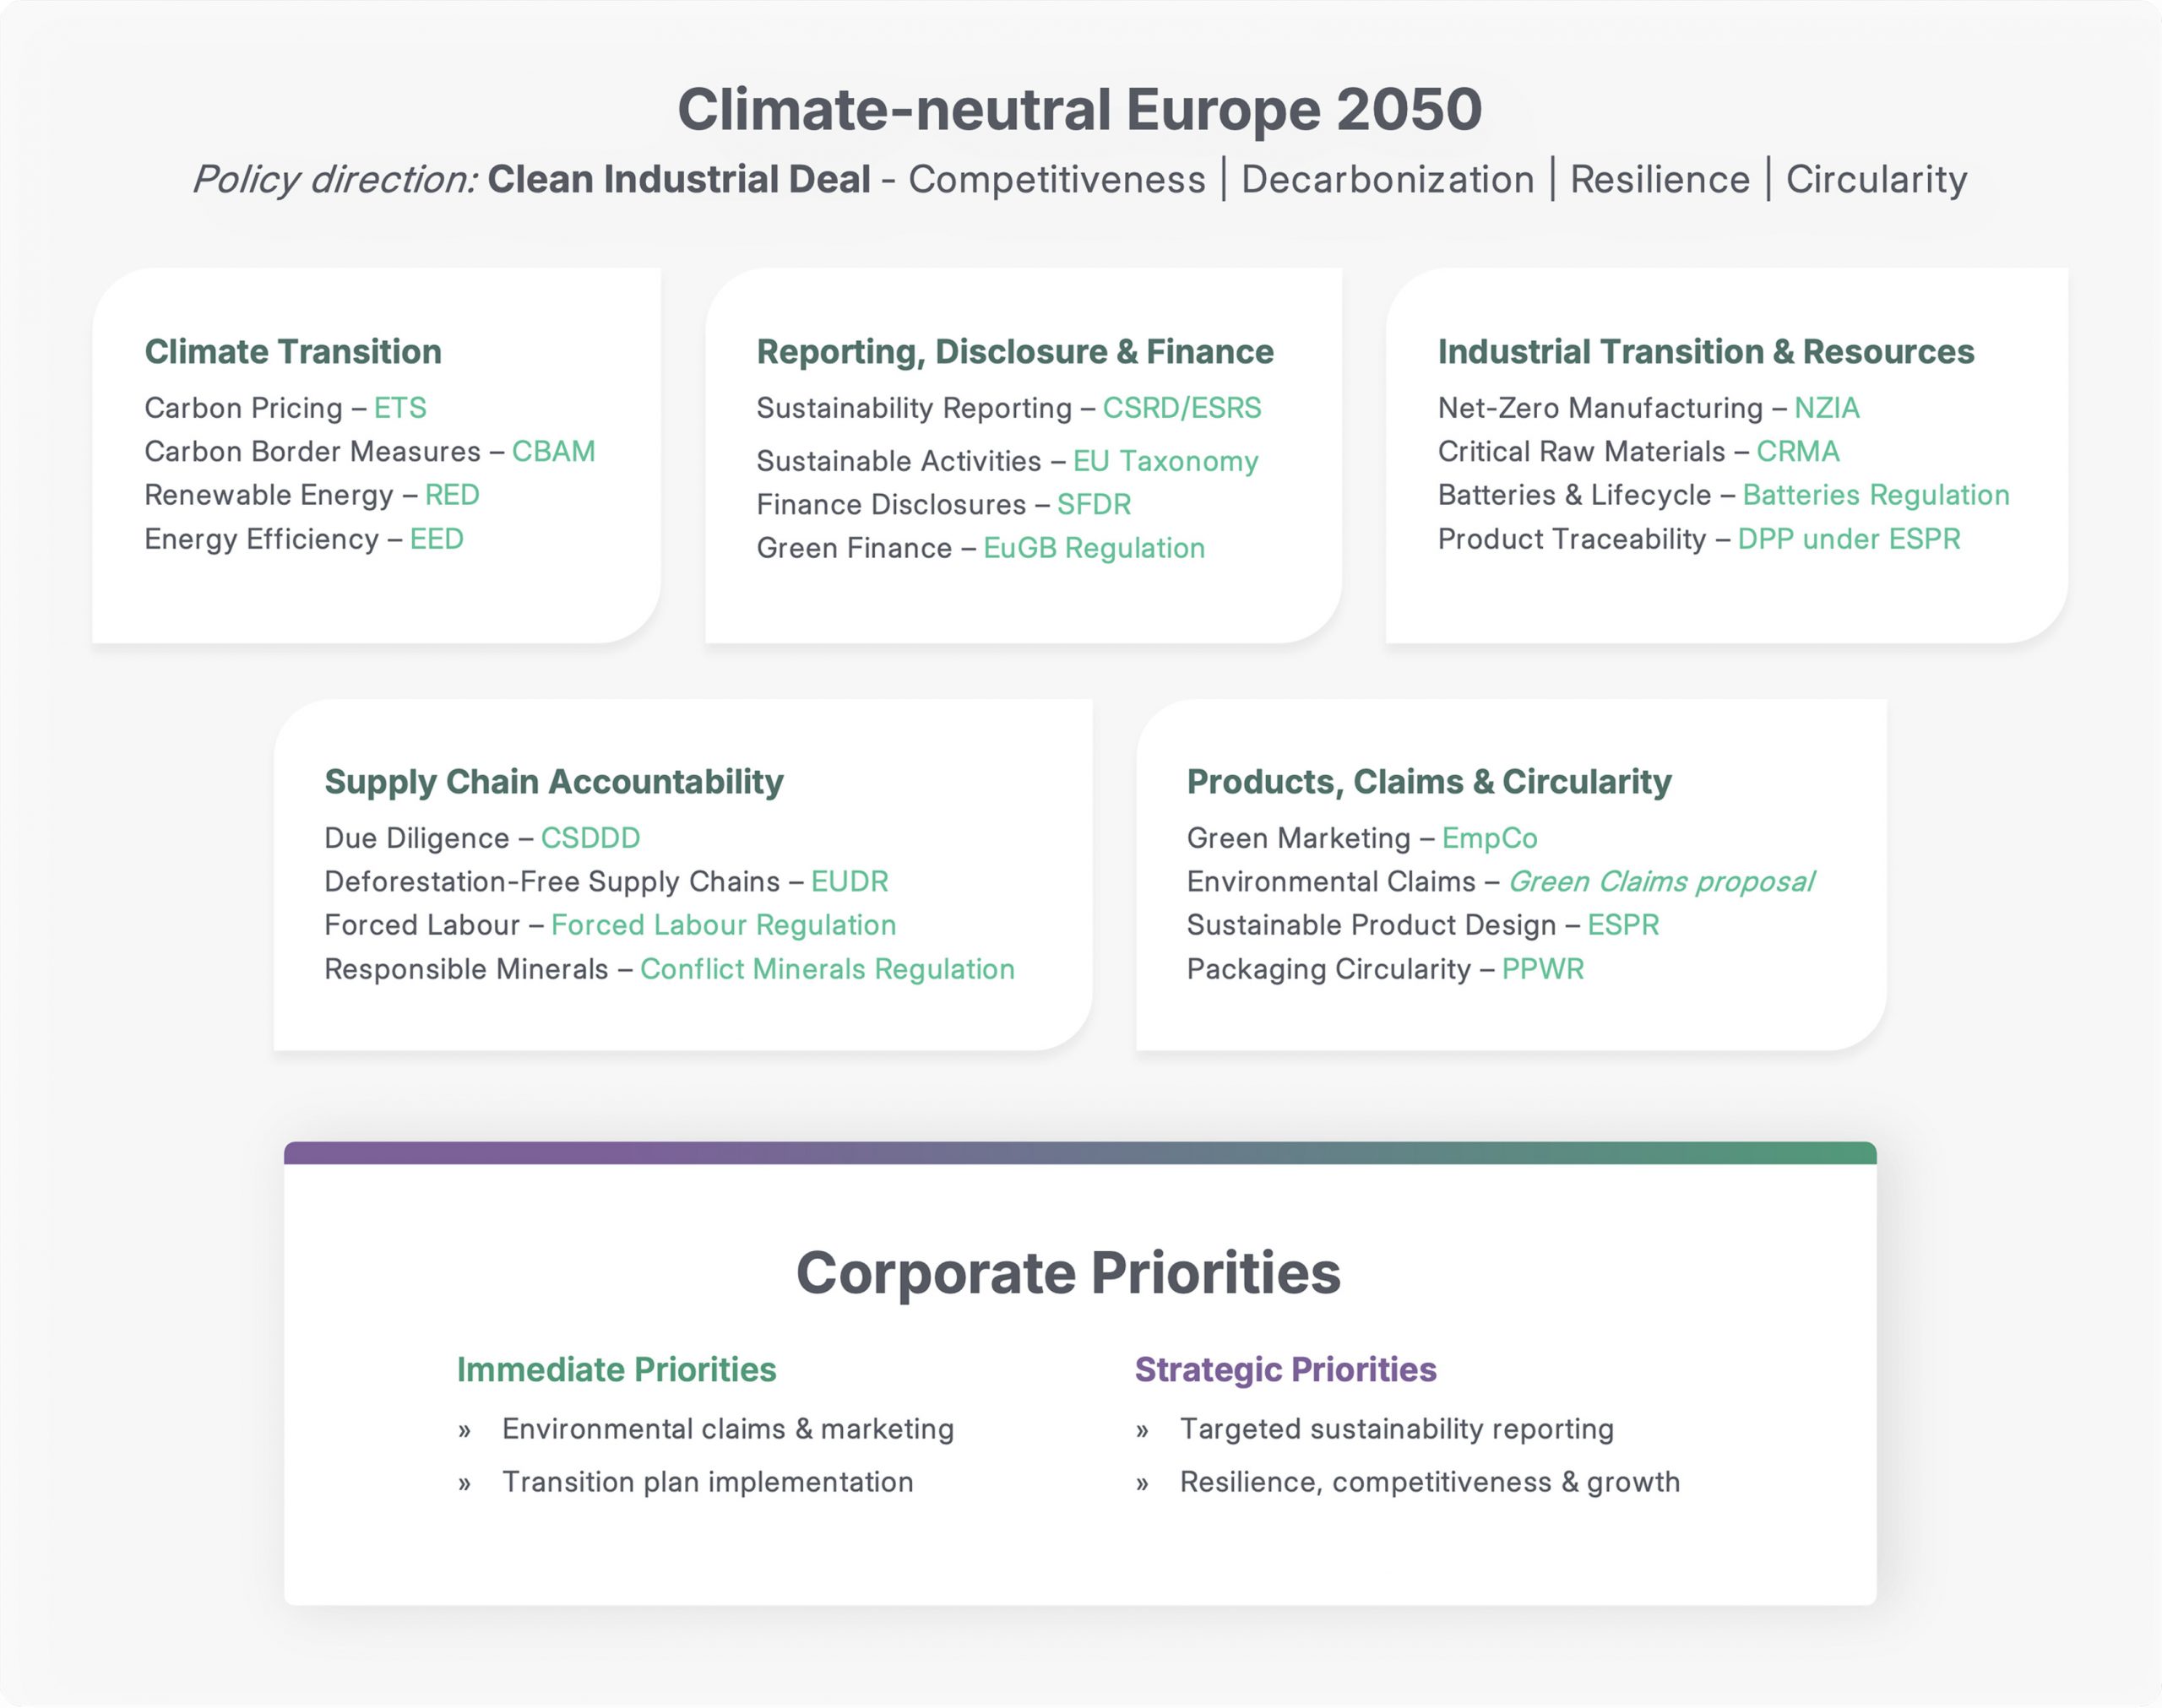
The European policy narrative is moving from reporting expansion towards implementation, industrial competitiveness and resilience. Adjustments to sustainability reporting may reduce the burden for some companies, but they do not remove expectations around climate transition planning, supply-chain accountability, product requirements or substantiation of environmental claims. The immediate priorities include credible claims and effective due diligence; the strategic priorities remain targeted reporting, transition delivery and enabling long-term value creation through effective management of sustainability-related risks and opportunities.
The European Sustainability Agenda: The Shift to Implementation
Evolving policy expectations are shifting corporate attention from reporting requirements to climate transition delivery, value-chain accountability and credible environmental claims.
3. Sustainability Reporting Must Support Decisions
A recurring message was that reporting is a means, not an end. The most useful disclosures show how risks and opportunities influence strategy, governance, capital allocation and performance. Investors remain interested in transition credibility, climate resilience and execution capability. This means fewer broad disclosures may be acceptable, but vague commitments are not: decision-useful information should connect targets with actions, investment, milestones and accountability.
4. Supply Chain Risk Management Must Integrate Operational, Environmental and Social Risks
Localising supply chains can improve control and transparency, while diversification can reduce exposure to climate, geopolitical and operational shocks. Neither option is inherently superior. Companies need to assess environmental, social and operational factors together, including the availability of alternative materials, supplier capacity, geographic concentration and human-rights performance. Climate and nature risk assessment and value-chain due diligence are becoming part of the same management discipline.
5. Climate Transition Credibility Depends on Execution and Awareness of Emerging Risks
Climate transition illustrates the wider execution challenge facing Nordic companies and their global peers. The issue is no longer whether companies have ambitions, but whether they can demonstrate a credible pathway to deliver them. Credibility depends on connecting targets, investment and execution. Participants also noted that established strengths on social issues require continued scrutiny as risks evolve, including labour conditions within companies’ own operations.
What Companies Should Prioritize Next
Companies should focus on targeted material actions: substantiate environmental claims, fund transition plans, integrate climate, nature, and social risks into sourcing, and retain disclosures that support business strategy and value creation. The broader challenge is alignment. Consumer expectations, investor requirements, and regulation do not always reinforce one another, and market forces alone may not drive action at the pace required. Regulation and investor scrutiny therefore remain essential, alongside corporate leadership, in translating shared climate, nature, and social priorities into investment and execution.
Strengthen your climate strategy and reporting with ISS-Corporate’s sustainability solutions »